

Vietnam Commercial Real Estate Market Outlook 2026: Rental Rates & FDI Trends
The commercial real estate Vietnam 2026 market is valued at over $20.10 billion, projected to grow at a 13.54% CAGR through 2034 — driven by high-tech manufacturing inflows and rising ESG compliance requirements across the office and industrial sectors.
Executive Summary: Vietnam CRE Market Drivers in 2026
The commercial real estate Vietnam 2026 market is valued at over $20.10 billion, projected to grow at a 13.54% CAGR through 2034. Prime Grade A office rents in Ho Chi Minh City CBD average $50–$65 /sqm/month, while industrial land leases in Southern key economic zones stabilize at $160–$250 /sqm/lease term, driven by high-tech manufacturing inflows and green ESG compliance requirements.
$20.10 billion in market value and a 13.54% CAGR. Vietnam’s CRE sector is entering a new era of growth.
Macroeconomic Climate & FDI Capital Inflows
Vietnam's macroeconomic trajectory establishes a resilient foundation for long-term real estate capital commitment. Strong GDP performance, stable inflation management, and rising industrial output continue to position the country as a primary beneficiary of global manufacturing supply chain realignments.
- Manufacturing Capital: >60% of total registered FDI targeted at industrial sectors
- Logistics Corridors: Expressway completions & deep-sea port expansions
- Regulatory Alignment: Implementation of revised Land Law & Real Estate Business Law
Supply Chain Realignment & High-Tech Manufacturing Demand
Multinational corporations are expanding operations in Vietnam to build resilient regional supply chain networks. High-value electronics, semiconductor assembly, and green energy component manufacturing dominate land absorption across primary industrial corridors.
Strategic Infrastructure Expansion
Government infrastructure expenditures are actively unlocking land bank value across secondary rings. Key infrastructure milestones include:
- Long Thanh International Airport: Phase 1 progress accelerating cargo hub development in Dong Nai.
- HCMC Ring Road 3 & Expressway Networks: Reducing transport lead times between industrial parks and port terminals.
- Northern Port Terminals: Expansion of deep-water berths at Lach Huyen (Hai Phong) supporting direct transpacific shipping lines.
Office Sector Performance: HCMC & Hanoi Market Deep Dive
The Vietnam office sector exhibits a clear flight-to-quality trend. Corporate occupiers are abandoning aging, non-certified assets in favor of modern, ESG-compliant developments featuring higher building specification standards.
Ho Chi Minh City Prime CBD & Thu Thiem Financial Corridor
Ho Chi Minh City maintains low vacancy across prime Grade A CBD assets. High multinational tenant demand keeps occupancy high for newly handed-over towers.
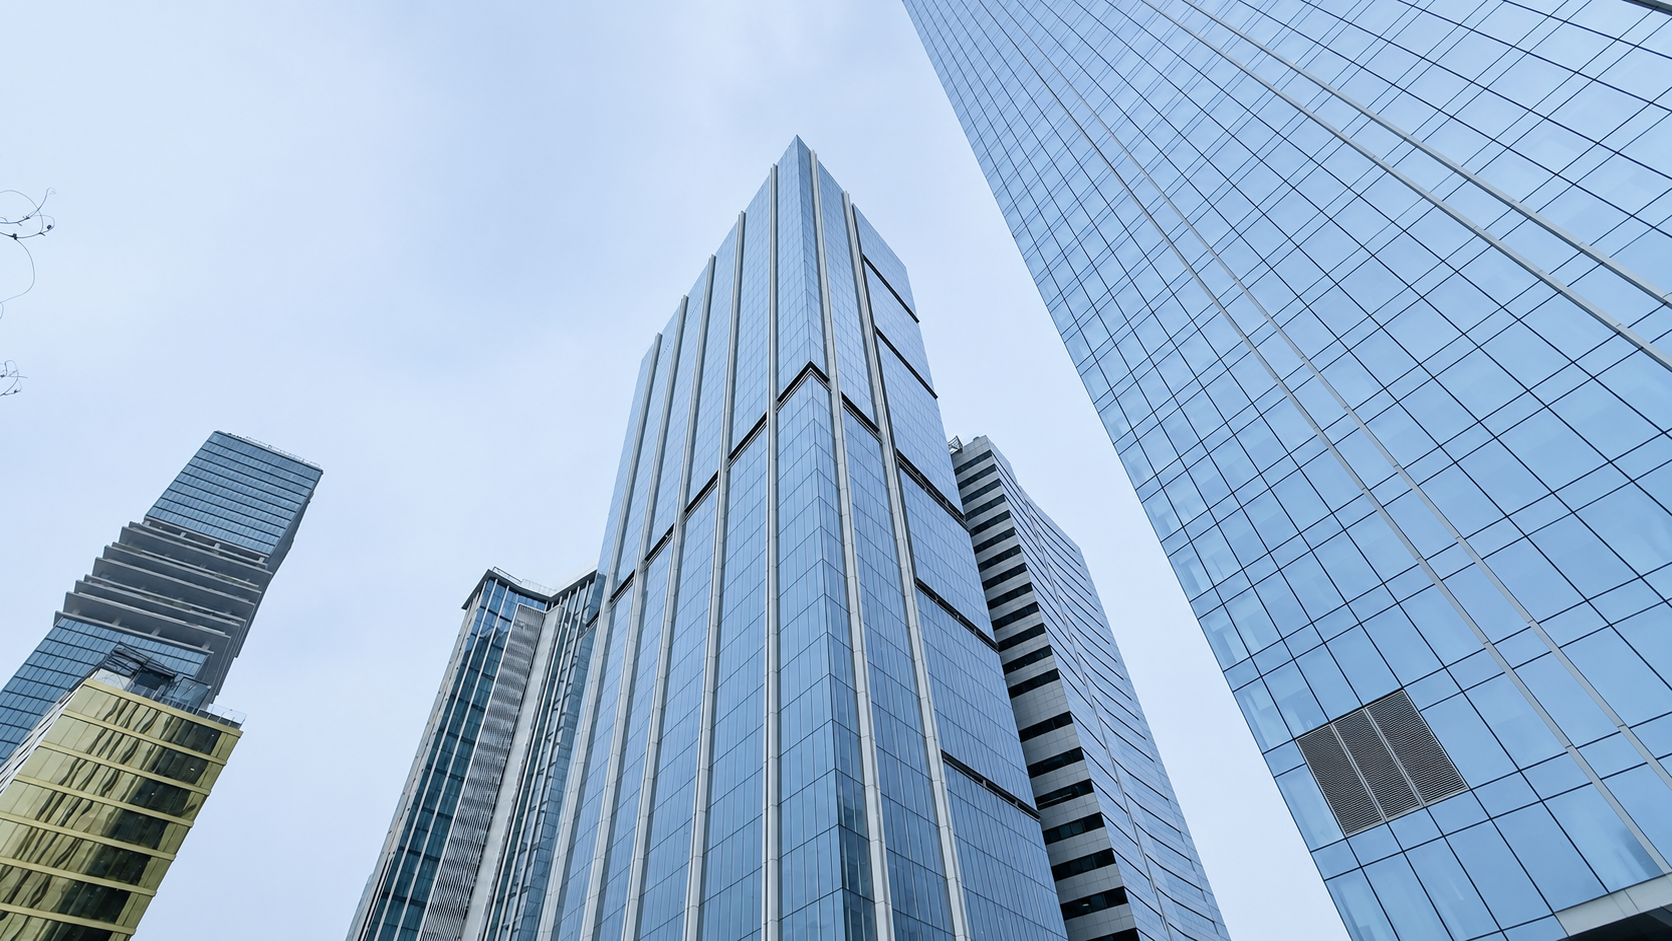
- District 1 Core: Rent remains premium due to tight supply. Prime occupiers are migrating to top-tier developments such as The Kross office space, which offers international structural specs alongside dual LEED Gold and WELL certifications.
- Thu Thiem Expansion Zone: Functions as a direct extension of the financial district. Large column-free floor plates (1,200–1,800 sqm) attract regional headquarters seeking spatial efficiency at competitive rental rates.
Hanoi Expansion & Decentralization Trends
Hanoi's office market is decentralizing rapidly away from Hoan Kiem. The West (Cau Giay, Nam Tu Liem) and Starlake urban zones account for the bulk of new Grade A absorption, driven by technology firms, government entities, and corporate tenants securing modern Hanoi Grade A office space.
Bars scaled to the upper end of each rental range, indexed against HCMC District 1 CBD.
Commercial Real Estat Vietnam 2026 Performance Benchmarks
The matrix below details key performance indicators across primary commercial asset classes in Ho Chi Minh City, Hanoi, and key industrial zones:
| Asset Class | Region / Sub-market | Avg. Rental Rate | Avg. Vacancy Rate | Primary Occupier Segment |
|---|---|---|---|---|
| Grade A Office | HCMC District 1 CBD | $50 – $65 /sqm/month | 11.5% – 13.0% | Banking, Legal, Finance, Tech HQs |
| Grade A Office | Thu Thiem (HCMC) | $38 – $48 /sqm/month | 15.0% – 18.0% | FinTech, Consulting, Regional HQs |
| Grade A Office | Hanoi West / Starlake | $28 – $38 /sqm/month | 12.0% – 14.5% | Tech, Diplomatic, Manufacturing HQs |
| Ready-Built Factory (RBF) | Southern Zone (Binh Duong, Dong Nai) | $4.80 – $6.20 /sqm/month | 8.5% – 10.0% | Precision Engineering, Automotive |
| Ready-Built Warehouse (RBW) | Northern Zone (Bac Ninh, Hai Phong) | $4.50 – $5.80 /sqm/month | 9.0% – 11.0% | E-commerce, 3PL, Cold Chain |
| Industrial Land Lease | Primary Hubs (National) | $160 – $250 /sqm/term | < 5.0% (Land Bank) | Heavy Industry, Semiconductor Plants |
Industrial & Logistics Sector: Expansion Beyond Tier-1 Hubs
Industrial real estate continues to lead total market transaction volume, representing over 26% of overall commercial market value. Occupiers are shifting from basic warehousing to high-specification, tech-enabled facilities.
Southern Industrial Corridor Dynamics
Binh Duong, Dong Nai, and Long An remain the core manufacturing epicenters of the South. Land scarcity in primary zones has accelerated multi-story warehouse developments and increased demand for specialized industrial and logistics advisory to evaluate secondary ring site selections.
Northern High-Tech Ecosystems
The Northern Economic Corridor leverages direct overland and sea freight connectivity to East Asian supply hubs. Bac Ninh, Hai Phong, and Quang Ninh continue to capture significant investment in semiconductor packaging, cleanroom warehousing, and consumer electronics production.
Legal Framework Realignment & Foreign Investment Regulations
The full implementation of the revised Land Law, Housing Law, and Real Estate Business Law provides greater statutory clarity and investment security for cross-border capital.
- Land Valuation Transparency: Standardized frameworks reduce land-use fee approval delays.
- Flexible Payment Structures: Improved options for annual vs. lump-sum land rental payments.
- Strict ESG Directives: National green building codes aligned with global institutional standards.
Institutional investors and multinational corporations actively work with specialized capital market advisors to structure joint ventures, evaluate land-use rights, and navigate cross-border capital deployment under these updated legal mechanisms.
Strategic Roadmap for Corporate Occupiers & Institutional Investors
Navigating the 2026 commercial real estate landscape requires a clear, data-driven approach:
- Advance Pre-Leasing Timelines: Engage in commercial negotiations 9–12 months prior to building completion to lock in favorable rental structures and fitting-out allowances.
- Prioritize Certified Assets: Focus portfolio acquisitions and lease agreements on properties with LEED, WELL, or EDGE credentials to eliminate future asset obsolescence risks.
- Optimize Spatial Footprints: Leverage column-free layout structures in emerging business hubs to consolidate fragmented satellite offices into unified, high-efficiency regional headquarters.
Optimize Your Strategy for Commercial Real Estate Vietnam 2026
Partner with NAI Vietnam to secure favorable lease terms, conduct site selections, or execute capital market transactions across Vietnam.
Connect with our Senior CRE Advisory Division
Email: info@naivietnam.com
Website: naivietnam.com